Life Insurance

Protect Today. Prepare for Tomorrow.

Life insurance can help provide financial protection for the people who depend on you. As an Independent Life Insurance Broker, I help clients understand and explore coverage options from multiple insurance companies so they can make informed decisions based on their needs, goals, budget and eligibility.

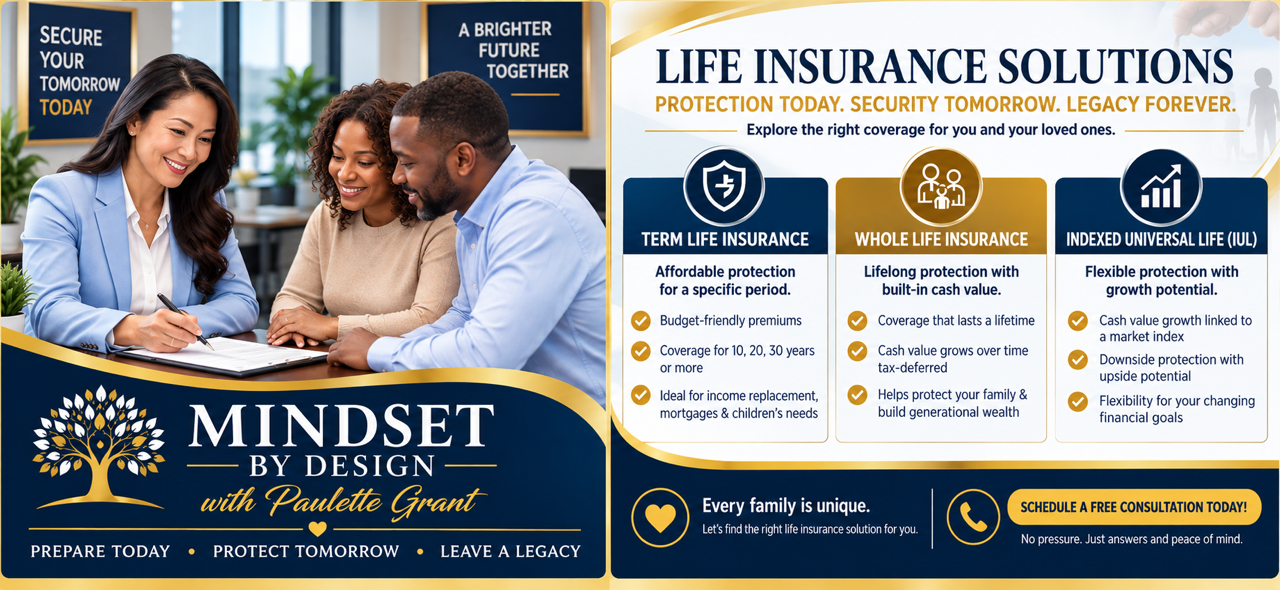
Mindset By Design life insurance services flyer

Term Life Insurance

Affordable protection for a specific period of time

Term life insurance provides coverage for a specified term — such as 10, 20, or 30 years, depending on the policy and carrier. It may be worth considering during important financial years.

Term life is often considered one of the more straightforward and affordable types of life insurance. Because it covers a defined period, premiums can be lower than permanent life insurance options — making it a popular choice for individuals who want substantial coverage during years when financial responsibilities are highest.

May be worth considering for:

  • Income replacement for your family
  • Mortgage protection
  • Family protection during child-rearing years
  • Debt protection
  • Children's education needs
  • Business-related protection

Coverage, premiums, and eligibility are subject to underwriting and the terms of the issuing insurance company.

Whole Life Insurance

Lifetime protection with cash value features

Whole life insurance is a form of permanent life insurance designed to remain in force for life when required premiums are paid and policy provisions are met.

Unlike term insurance, whole life policies generally include a cash-value component that can accumulate over time. Premiums are typically fixed, and the death benefit is guaranteed as long as the policy remains in force. Whole life may be considered by individuals looking for permanent coverage, predictable premiums, final-expense protection, or legacy planning.

May be worth considering for:

  • Permanent lifetime coverage
  • Cash value accumulation over time
  • Fixed, predictable premiums
  • Legacy and estate planning
  • Final expense coverage

Coverage, premiums, and eligibility are subject to underwriting and the terms of the issuing insurance company. Cash value accumulation is subject to policy terms and charges.

Final Expense Insurance

Help protect your family from the financial burden of final expenses

Funeral and burial expenses can place an unexpected financial burden on the people you love. Final Expense insurance is generally a smaller permanent life insurance policy designed to help beneficiaries handle expenses following your passing.

Planning ahead with Final Expense insurance can help your loved ones focus on each other instead of worrying about how they'll cover costs. Depending upon the beneficiary's needs, proceeds could help with funeral and burial costs, outstanding bills, or other expenses. Final Expense policies may be available with simplified underwriting, which can make them accessible to individuals who may not qualify for larger policies.

May be worth considering for:

  • Funeral and burial costs
  • Outstanding bills and debts
  • May be available with simplified underwriting
  • Often considered by seniors or those with health concerns

Coverage, premiums, and eligibility are subject to underwriting and the terms of the issuing insurance company.

Indexed Universal Life (IUL)

Understand IUL before you decide

Indexed Universal Life, commonly called IUL, is a type of permanent life insurance that combines a death benefit with a cash-value component.

Interest credited to the policy's cash value can be linked to the performance of a market index, subject to the particular policy's terms, caps, participation rates, floors, charges, and other provisions. IUL can be complex, which is why education is important. My goal is to help you understand how an IUL works, its potential benefits, its costs and limitations, and the questions you should ask before purchasing a policy.

May be worth considering for:

  • Permanent death benefit protection
  • Cash value linked to a market index (subject to caps and floors)
  • Flexible premium payments (subject to policy minimums)
  • Requires careful review of policy terms, charges, and illustrations

IUL policies are complex financial products. Interest credited is subject to caps, participation rates, floors, and policy charges. Past index performance does not guarantee future results. This is not investment advice. Coverage and values are subject to the terms of the issuing insurance company.

Not Sure Which Option Is Right for You?

That's exactly what a consultation is for. I'll take the time to understand your situation and help you explore what may be available.

Mindset By Design

MINDSET BY DESIGN

with Paulette Grant

Independent Life Insurance Broker & Insurance Business Consultant

Prepare Today • Protect Tomorrow • Leave a Legacy

© 2026 Mindset By Design. All rights reserved.

Paulette Grant is an independent life insurance broker. Life insurance products are subject to underwriting approval and the terms of the issuing insurance company. Coverage availability and premiums vary. Information on this website is provided for general educational and informational purposes and should not be considered financial, legal, or tax advice.